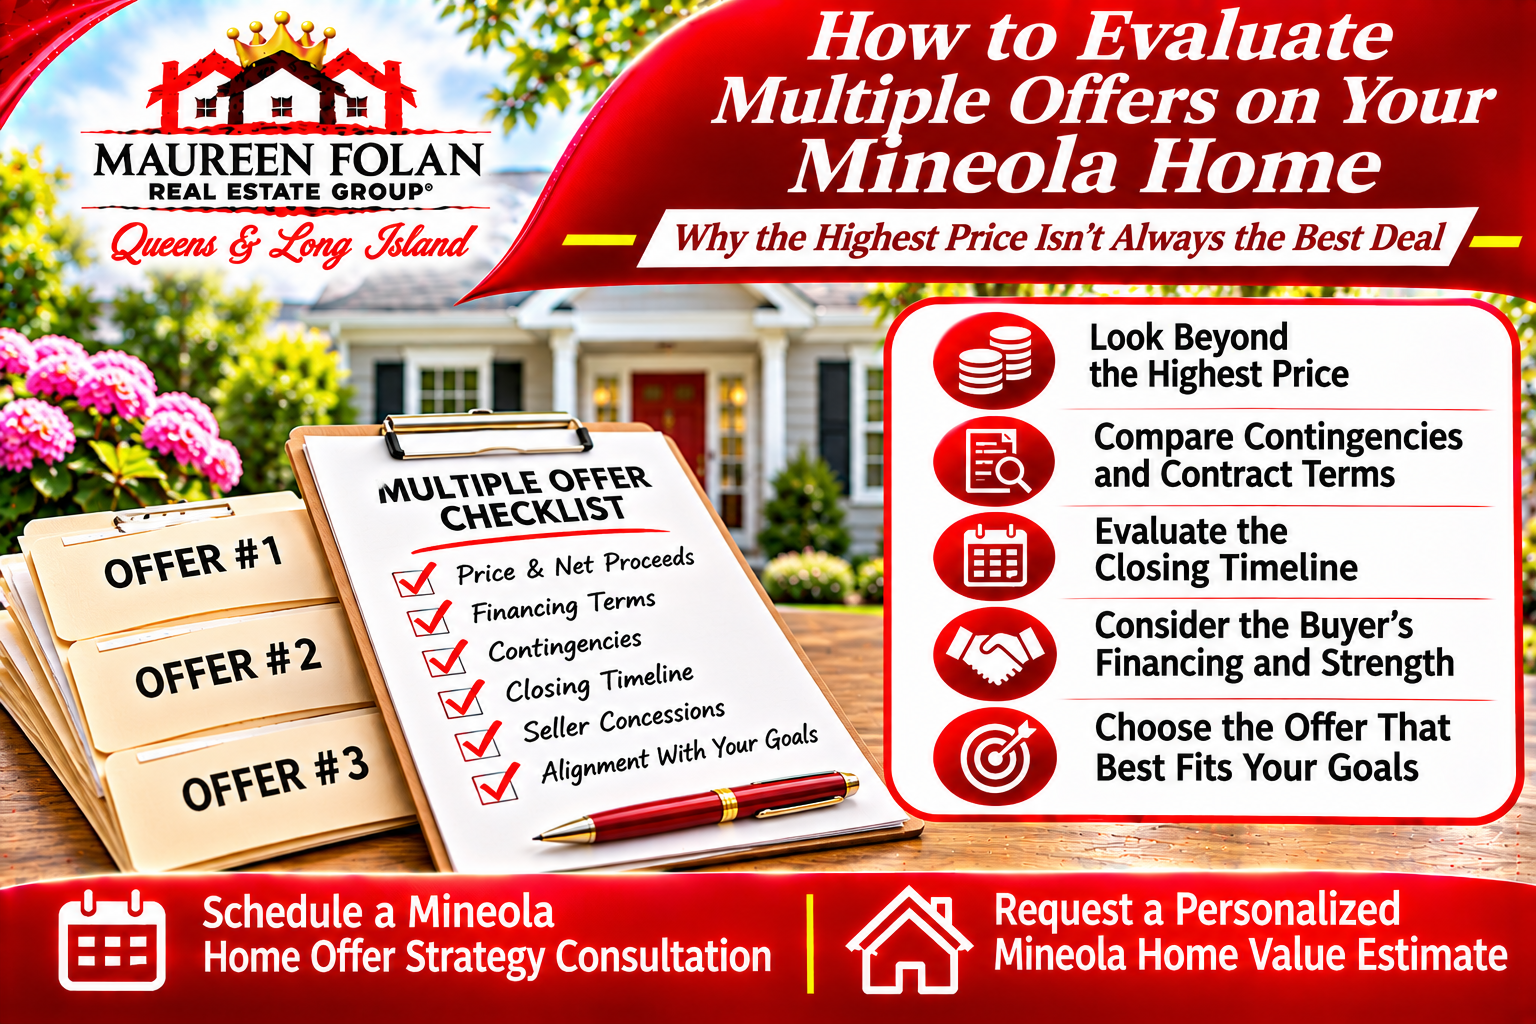
 How to Evaluate Multiple Offers on Your Mineola Home: Why the Highest Price Isn't Always the Best Deal
How should you compare multiple offers on your Mineola, NY home, and is the highest offer always the best one?
When evaluating multiple offers on a home in Mineola, NY, you should compare more than the proposed purchase prices. Financing terms, contingencies, deposit provisions, closing timelines, property-condition requests, and the buyer's ability to complete the transaction can all affect the outcome. The strongest offer is the one that provides an appropriate combination of price, terms, and alignment with your selling goals.
Evaluating Multiple Offers on a Home in Mineola, NY
If you're researching evaluating multiple offers on a home in Mineola NY, you may be preparing to list your property or already reviewing offers.
Receiving more than one offer can create an important decision.
One buyer may propose the highest price.
Another may offer terms that better support your moving timeline.
A third may have fewer conditions.
How do you compare them?
The answer isn't simply to choose the largest number.
You need to evaluate the complete offer and understand what each buyer is proposing.
That process begins with your priorities as the seller.
Start With Your Selling Goals
Before comparing offers, clarify what matters most.
Are you trying to maximize your net proceeds?
Do you need to coordinate the sale with another purchase?
Is your property vacant?
Are you relocating?
Do you need a particular closing timeline?
Are there property-condition or documentation issues that could affect the transaction?
Your goals influence how you evaluate competing proposals.
An offer that works well for one seller may not be the strongest choice for another.
Understand the Difference Between Offer Price and Net Proceeds
The proposed purchase price is important.
But it isn't the same as the amount you'll receive after closing.
Your net proceeds may be affected by your mortgage payoff, applicable transaction expenses, negotiated concessions, and other obligations.
For example, imagine two hypothetical offers:
| Item | Offer A | Offer B |
|---|---|---|
| Proposed purchase price | $850,000 | $835,000 |
| Requested seller concession | $15,000 | $0 |
| Price less stated concession | $835,000 | $835,000 |
These figures are illustrative only and do not represent current Mineola market data or a complete net-proceeds calculation.
The example shows why comparing purchase prices alone may be misleading.
Both offers have the same amount after the stated concession, before other expenses and adjustments.
The contractual details still matter.
Financing Terms Can Affect the Transaction
Buyers may propose different financing arrangements.
Some may use mortgage financing.
Others may propose purchasing without a mortgage contingency or with other financing terms.
However, the absence of a mortgage contingency doesn't automatically guarantee that a transaction will close.
Review the actual terms and available supporting information.
Your attorney and appropriate professionals can help evaluate the implications of each proposal.
What Is a Mortgage Contingency?
A mortgage contingency is a contractual provision that may allow a buyer certain rights if financing cannot be obtained under the agreed conditions.
The exact terms depend on the contract.
When comparing offers, understand whether financing contingencies are proposed and how they may affect the transaction.
Your attorney can explain the legal implications.
Don't assume every financing contingency operates the same way.
What About a Cash Offer?
A cash offer may have a different financing structure from an offer involving mortgage financing.
However, cash doesn't automatically mean the transaction is free from conditions or potential complications.
The buyer may still have due diligence requirements, contractual contingencies, or other obligations.
Evaluate the complete proposal.
Don't assume that one financing label establishes the strongest offer.
Deposit Terms Matter
In New York residential real estate transactions, contract deposits and related provisions are important parts of the agreement.
The amount, timing, handling, and consequences of a deposit depend on the contract and applicable law.
Your attorney can explain the proposed terms.
Don't assume a larger deposit automatically makes an offer better without understanding the complete agreement.
Compare Closing Timelines
One buyer may propose a relatively short closing timeline.
Another may request additional time.
The strongest arrangement depends on your circumstances.
If you've already purchased another property, you may prefer a particular schedule.
If you're still searching for your next home, flexibility may be valuable.
However, closing dates can be affected by financing, title matters, contractual requirements, and other factors.
Don't assume a proposed date is guaranteed.
If You're Buying Another Property, Timing Becomes Especially Important
Suppose you're selling your Mineola home and purchasing another property.
You may need the sale proceeds for your next purchase.
In that situation, the timing of both transactions may be closely connected.
Before accepting an offer, consider:
- Your expected net proceeds
- Your next purchase timeline
- Available financial reserves
- Contractual obligations
- Potential closing delays
- The flexibility you may need
Your attorney and appropriate professionals can help evaluate transaction-specific considerations.
Understand Home Sale Contingencies
A buyer may propose making their purchase dependent on selling another property.
The exact terms depend on the proposed agreement.
Such a contingency may introduce additional timing considerations.
Before accepting it, understand what the buyer is proposing and how it may affect your sale.
Your attorney can explain the legal implications.
Don't assume every home sale contingency presents the same circumstances.
Inspection and Property-Condition Terms
Buyers may want to investigate a property's condition before completing the transaction.
Depending on the proposal, inspection-related terms may affect negotiations.
If your Mineola home has older components, renovations, additions, or deferred maintenance, those details may become relevant.
Review the proposed conditions carefully.
Your attorney and appropriate professionals can help evaluate transaction-specific questions.
What If Your Home Is Being Sold As-Is?
An as-is sale may be part of your marketing strategy.
However, selling as-is doesn't automatically eliminate applicable disclosure obligations, buyer due diligence, contractual responsibilities, or other legal requirements.
The specific terms matter.
Before comparing offers, understand what each buyer is requesting and what your contract would require.
Evaluate Buyer Requests for Repairs or Credits
An offer may include requests involving repairs, credits, or other adjustments.
Those requests can affect your net proceeds and transaction responsibilities.
Don't evaluate them solely by the purchase price.
Consider the complete financial and contractual arrangement.
Your attorney and appropriate professionals can help clarify the implications.
Understand the Property's Documentation Before Negotiating
Mineola is an incorporated village in Nassau County.
Certain property-related matters may be administered through village or other applicable authorities.
Official information is available through the Village of Mineola.
If your property has additions, conversions, or significant renovations, investigate relevant permits and records.
Your attorney and qualified professionals can help evaluate transaction-specific requirements.
Accurate documentation can help you respond to buyer questions during negotiations.
Mineola Property Taxes May Be Part of Buyer Questions
Property taxes can influence how buyers evaluate ownership costs.
Mineola property owners should verify applicable taxing jurisdictions and current tax obligations.
Official assessment information is available through the Nassau County Department of Assessment.
Current tax amounts may reflect exemptions or circumstances associated with the existing owner.
A future buyer's obligations may differ.
Accurate information can help buyers evaluate the property without relying on unsupported assumptions.
How to Compare Multiple Offers Side by Side
A structured comparison can help you avoid focusing on only one detail.
Consider this framework:
| Offer Consideration | Buyer A | Buyer B | Buyer C |
|---|---|---|---|
| Proposed purchase price | Review | Review | Review |
| Financing terms | Review | Review | Review |
| Mortgage contingency | Review | Review | Review |
| Home sale contingency | Review | Review | Review |
| Deposit provisions | Review | Review | Review |
| Inspection terms | Review | Review | Review |
| Requested concessions | Review | Review | Review |
| Proposed closing timeline | Review | Review | Review |
| Other contractual conditions | Review | Review | Review |
| Alignment with your goals | Evaluate | Evaluate | Evaluate |
The objective isn't to create a simplistic score.
It's to understand the complete differences between proposals.
Don't Assume the Highest Offer Is the Strongest
Imagine one buyer offers a higher price but proposes several conditions.
Another offers slightly less with different terms.
Which is stronger?
The answer depends on the actual proposals and your circumstances.
A higher price may be worthwhile.
But the terms could also affect your net proceeds, timing, or transaction obligations.
Review the complete offers before deciding.
Don't Assume the Lowest Offer Is Automatically Weaker
The opposite assumption can also be misleading.
A lower-priced offer may include terms that better align with your timeline or preferences.
However, that doesn't mean you should automatically accept less.
The appropriate decision requires comparing both financial and contractual considerations.
Your attorney can help clarify the legal terms.
What If Two Offers Are Very Similar?
When offers are close, smaller differences may become more important.
You may want to compare financing arrangements, proposed contingencies, deposit terms, closing timing, and other conditions.
Your priorities should guide the evaluation.
Don't invent certainty where none exists.
Every transaction carries some degree of uncertainty.
Should You Ask Buyers for Their Best and Final Offers?
Depending on the circumstances, a seller may consider asking interested buyers to submit their strongest proposals.
However, the appropriate approach depends on the transaction, applicable rules, and your strategy.
Your real estate professional can help you evaluate the available options.
The goal is to manage negotiations fairly and professionally while protecting your interests.
Avoid Creating Artificial Urgency
Multiple-offer situations can create pressure.
But decisions should still be based on accurate information.
Don't assume every buyer will improve their offer.
And don't make claims about competing proposals that aren't supported by the facts.
A clear negotiation process is more useful than unnecessary pressure.
Keep Your Pricing Strategy Connected to Market Evidence
Even if you receive multiple offers, your property's market value should still be evaluated in context.
Relevant comparable sales, current competition, condition, layout, documented improvements, and location remain important.
An offer above asking price isn't automatically evidence that every term is favorable.
Likewise, an offer below asking price isn't automatically unreasonable.
Evaluate the complete market and transaction circumstances.
What If an Offer Falls Through?
Not every accepted offer results in a completed sale.
The reasons can vary.
If a transaction doesn't proceed, review what happened with your attorney and appropriate professionals.
Then reassess the property's market position and available options.
Avoid assuming the same outcome will occur with every buyer.
Preserve Your Next-Move Flexibility
If you're purchasing another property, consider how the selected offer affects your plans.
Will the proposed timing work?
Do you have sufficient financial reserves?
What happens if the closing date changes?
Does the offer support your preferred moving sequence?
The strongest transaction strategy should connect your current sale with your next step.
A Mineola Multiple-Offer Evaluation Checklist
Before accepting an offer, review:
- Your selling goals and preferred timeline.
- The proposed purchase price.
- Estimated net proceeds.
- Requested concessions or credits.
- Financing arrangements.
- Mortgage contingency terms.
- Home sale contingency terms, if any.
- Deposit provisions.
- Inspection and property-condition terms.
- Other contractual obligations.
- Proposed closing timeline.
- Property documentation questions.
- The buyer's proposed transaction structure.
- How the offer supports your next move.
- Your attorney's review of the legal terms.
This process can help you compare offers more effectively.
Final Takeaway: Evaluating Multiple Offers on a Mineola Home
When evaluating multiple offers on a home in Mineola NY, don't focus exclusively on the highest purchase price.
Review the complete proposals.
Compare financing terms, contingencies, deposit provisions, requested concessions, closing timelines, and other contractual conditions.
Estimate your likely net proceeds.
Understand the implications of each offer with your attorney.
And consider how the selected transaction supports your next move.
As Maureen Folan, Queens & Long Island Real Estate Expert, I help homeowners evaluate offers in the context of their property, current competition, and selling goals.
Because receiving multiple offers is only one part of the process.
The objective is to choose the offer whose price, terms, and timing best support a successful transaction for your circumstances. 
Schedule a Mineola Home Offer Strategy Consultation
Preparing to sell your Mineola home or reviewing competing offers?
Schedule a Mineola Home Offer Strategy Consultation with Maureen Folan Real Estate Group.
We'll discuss your property's market position, current competition, selling goals, preferred timeline, and the practical considerations involved in comparing offers.
You can also request a Personalized Mineola Home Value Estimate to better understand your property's potential market position before listing.
Whether you're moving elsewhere on Long Island, relocating toward Queens, or planning another transition, let's develop a strategy around your property and your goals.
Maureen Folan
Queens & Long Island Real Estate Expert
Maureen Folan Real Estate Group
MaureenFolan.com